

Related bodies corporate for payroll tax
Learn about what circumstances apply for corporations to be grouped.
On this page:
Related bodies corporate that carry on a business are automatically grouped.
‘Corporation’ is defined in section 57A of the Corporations Act 2001 (Cwlth).
Corporations are related if any of the following apply:
- One corporation controls the board composition of another corporation.
- One corporation can control more than 50% of votes in a general meeting of another corporation.
- One corporation holds more than 50% of the share capital of another corporation.
The first corporation is called a holding company. The second corporation is called a subsidiary.
Any related bodies corporate are grouped, even if they have holding companies overseas.
Related bodies corporate cannot apply for an exclusion from the group.
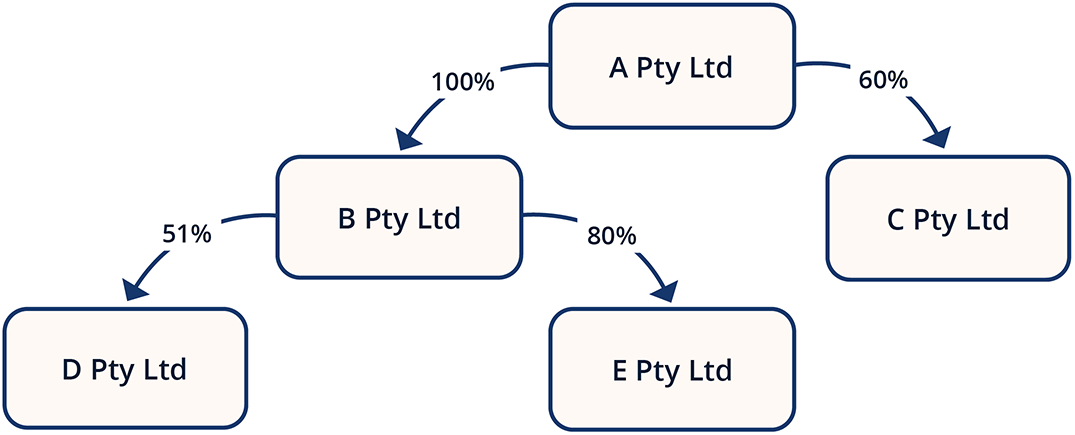
As an example:
- A Pty Ltd is the holding company of B Pty Ltd and C Pty Ltd, with more than 50% of the voting shares of each company.
- B Pty Ltd is the holding company of D Pty Ltd and E Pty Ltd.
- A Pty Ltd is the ultimate holding company.
All the companies in this example are grouped.
Last updated: 11 September 2026